What does a public adjuster do, and do I need one?
A public adjuster is licensed by the state to represent the policyholder in an insurance claim, and is paid a percentage of what the claim recovers. Your insurer's adjuster works for your insurer. Your roofer is not licensed to negotiate on your behalf at all. If the carrier's scope is short and you have no way to argue it, the public adjuster is the person whose job that is.
There are three adjusters and only one of them works for you
The company adjuster is the one your insurer sends. They are usually reasonable and they are paid by the company whose money is being spent. The independent adjuster is a contractor the carrier hires when it has more claims than staff, which is what happens after a big hail event; they work to the carrier's guidelines too.
The public adjuster is the third one, and the only one on your side of the table. They are licensed by the Texas Department of Insurance, they represent you, and they take a percentage of the settlement rather than an hourly fee. That percentage is the reason to think about whether you need one at all.
A roofing contractor is none of these. A roofer can document damage, meet the adjuster on site and write a scope, and that is where the line is. Anyone offering to handle your claim, waive your deductible or negotiate for you is describing something a contractor is not allowed to do.
The point at which one is worth it
Most claims do not need one. The adjuster comes out, the scope is broadly right, the roof gets replaced and everybody moves on. The claims that need one look different: a scope that covers two slopes when four are damaged, a settlement that will not pay for the roof, a denial you believe is wrong, or a file that has gone quiet for months.
On one claim, the offer was $1,500 for a roof and a water-damaged bedroom ceiling. A public adjuster took that claim on, fought it, and it ended in an award of $15,800 with nothing out of pocket, deductible included. That is the shape of a claim that needed one.
It is worth being honest about the maths. A public adjuster taking ten per cent of $15,800 is a good outcome for a homeowner who was offered $1,500. A public adjuster taking ten per cent of a claim that was going to settle correctly anyway is money you did not need to spend.
What a roofer should be doing while that happens
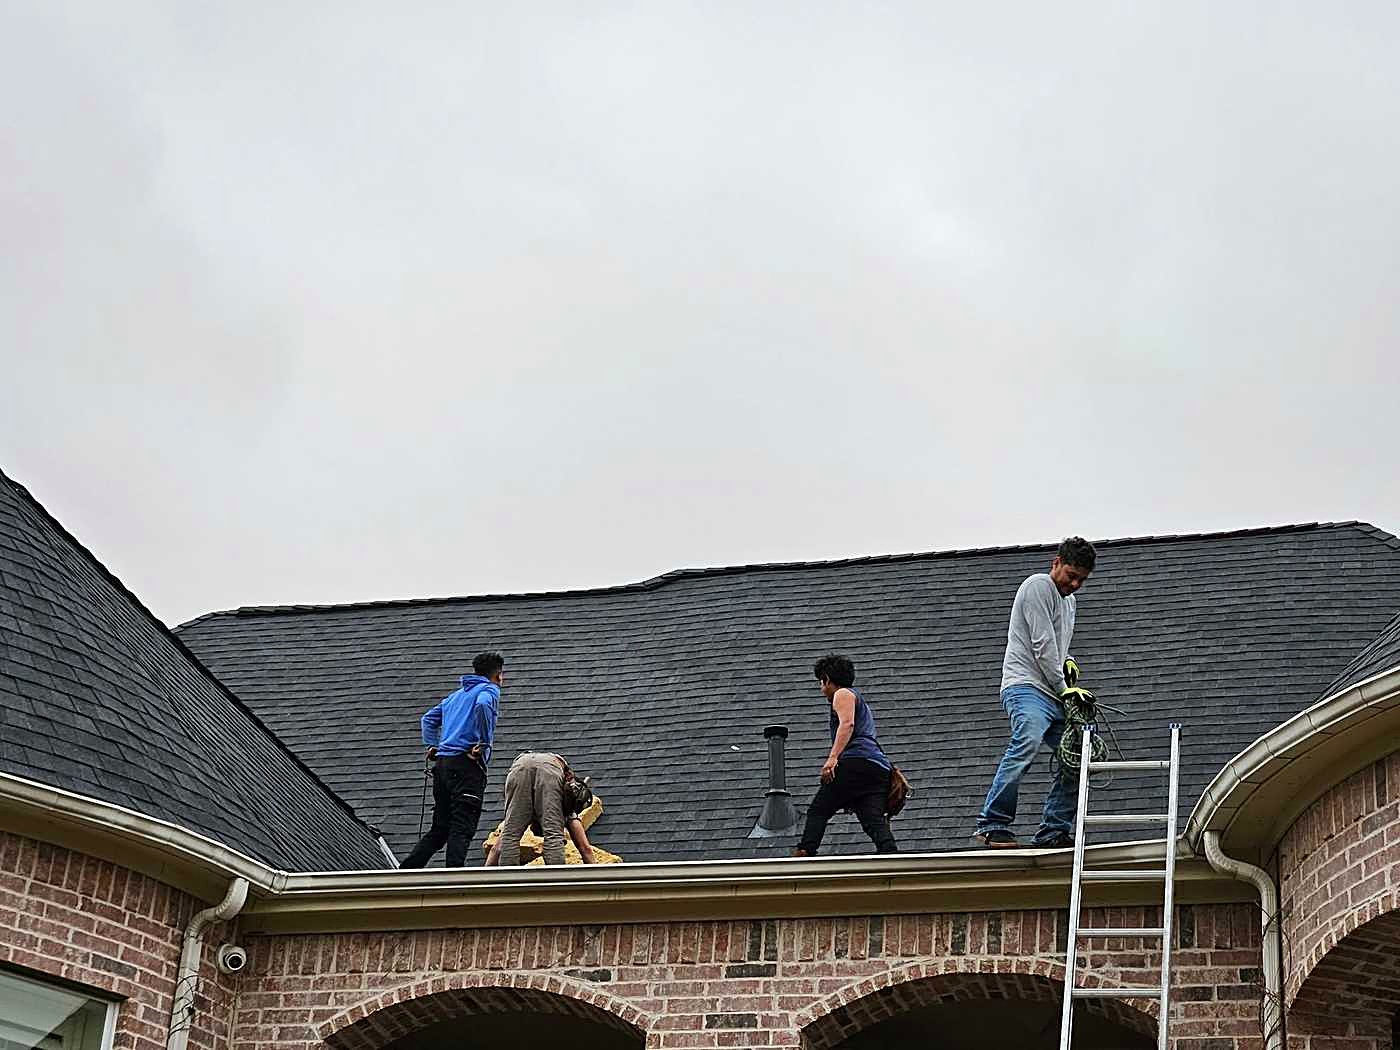
Documentation, and nothing that requires a license. Every slope photographed, the soft metal checked for impressions, the measurements taken, the damage written up in the order an adjuster reads it, and somebody on site when the adjuster comes out so the same roof is being discussed.
The other thing is patience. Claims that go the distance take months, and one on this profile took two years before the roof went on. A contractor who has moved on to the next job is not much use to you in month nine.
Related questions
Can my roofer waive my deductible?
No, and in Texas it is illegal to offer. A contractor who advertises it is telling you something useful about how they operate.
How much does a public adjuster cost?
A percentage of the settlement, agreed before they start. Ask for the number in writing and ask what happens if the claim does not improve.
Can I get one after the claim is closed?
Sometimes a closed claim can be reopened, particularly if new damage is found or the original scope missed something. It is worth asking rather than assuming.